The Shadow Fleet Is Sinking

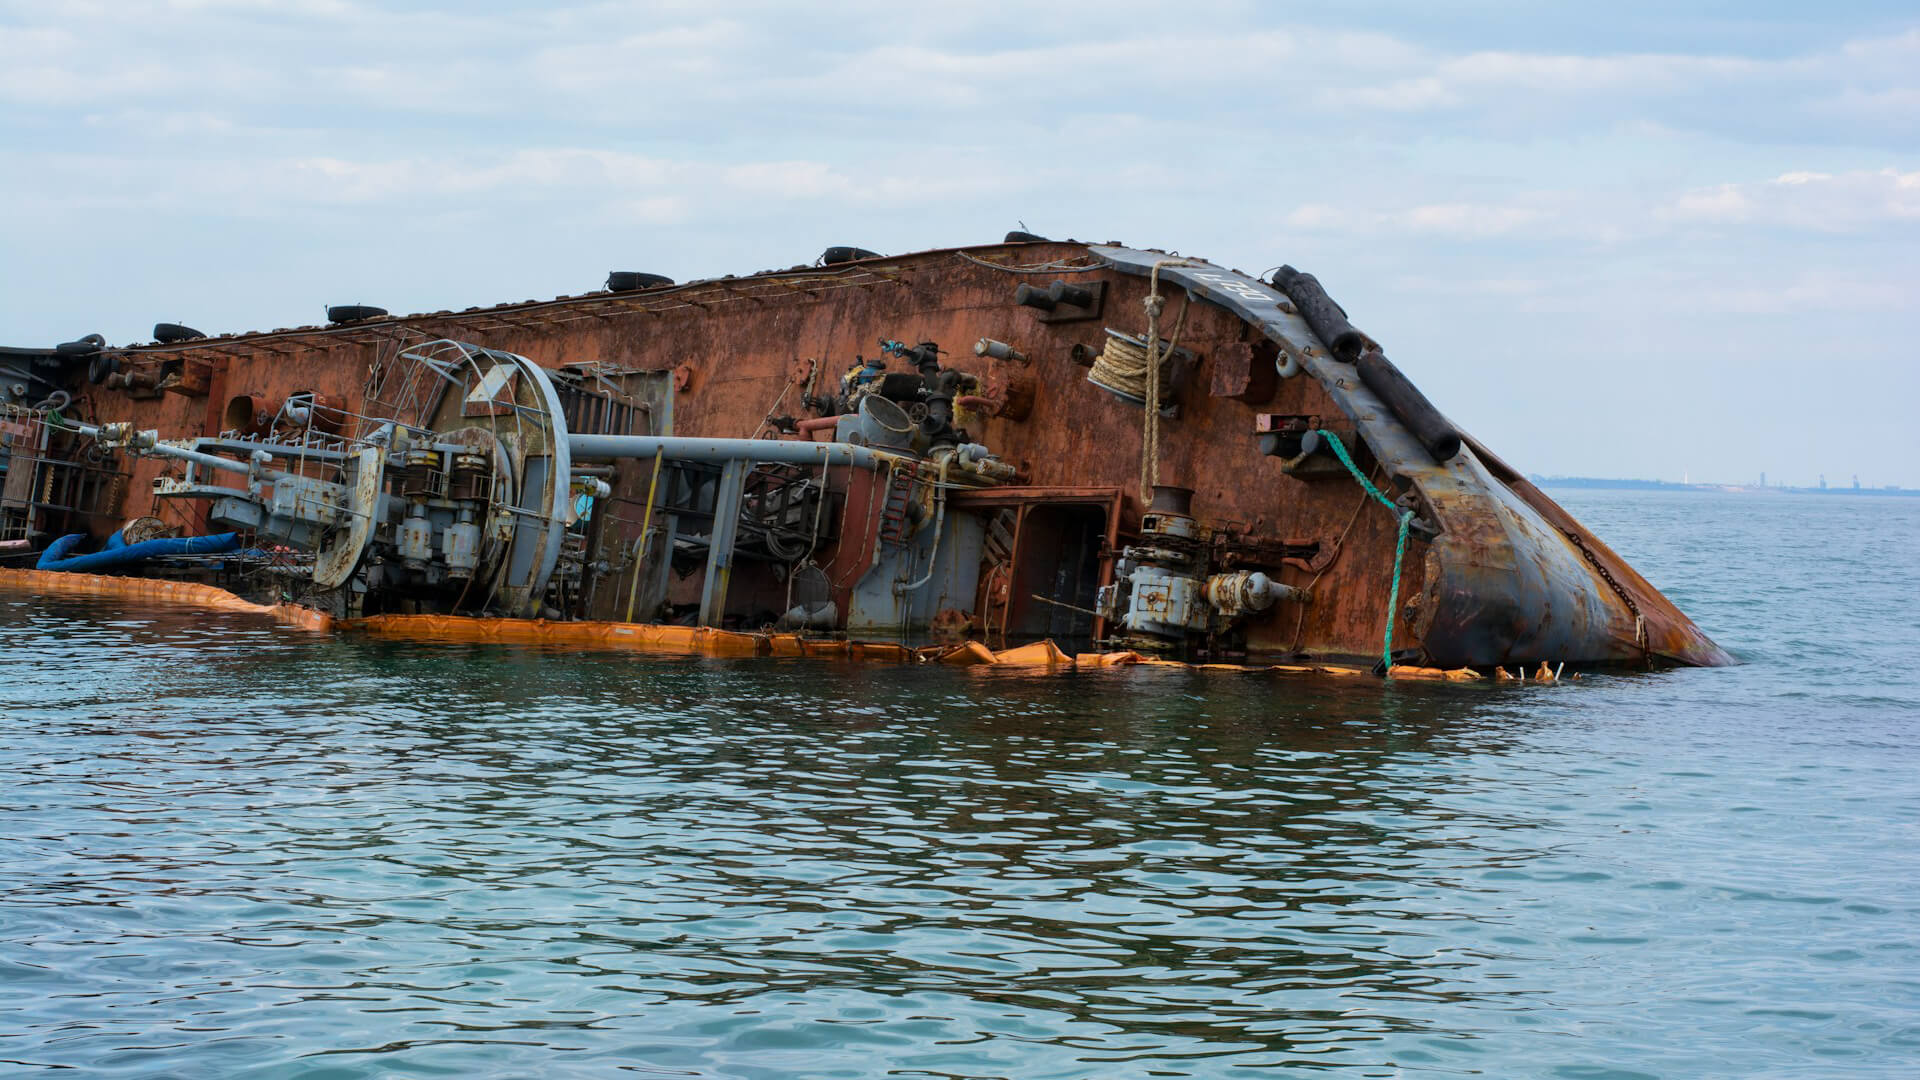
a ship sinking in the ocean

The first of Russia and Iran’s aging shadow fleet is sinking. The tanker is carrying ~1 million barrels of crude bound for India, but that oil is already leaking into the water off the Omani coast.

Beyond the environmental disaster, the next question is that of insurance. Since the shadow fleet is “covered” by Russia’s state-backed insurance system, whether they pay out or not will determine just how much longer the decrepit shadow fleet can operate.

Transcript

Hey everybody. Peter Zeihan here, coming to you from the peak of Sheridan. But today we’re going to talk about the Russian and Iranian shadow fleets and a ship that is in the process of sinking off the Omani coast in the Middle East. If you remember, we’ve got sanctions on Iran, we’ve got sanctions on Russia. And so both countries have turned to what are called shadow fleets, unregistered vessels that are old and were destined to be scrapped, that take out insurance from the Russian government. And the first one of them is now actually sinking. And we’re honestly pretty lucky here. It’s been four years since the Ukraine war got going, and in that time you would expect more of these things to go down. But it wasn’t until recently that Ukraine just started to openly attack the shadow fleet in the Black Sea, and so far they haven’t actually tried to sink anything. Now we’ve got one that is on its own, that is taking Russian crude to India. It is now sinking. Its the Caroline Bezengi, I believe is the name. Carries about a million barrels a day or carries about a million barrels. And it is now sinking off the coast of Oman, already in oil spill, it’s about 400km², and we’re already seeing oil starting to make landfall on some of the Omani islands. 

It’s in the last 48 hours, it’s condition has deteriorated significantly and it is very clearly taking on water. I can’t tell you when it’s going to sink, but there’s really no hope that it’s going to make it to its destination at this point. And so we’re talking about an ecological disaster that is at least three times as bad as what happened with the Exxon Valdez. 

It’s an open question whether anyone will let this thing dock because it’s just going to leak in port then. But at least one of the compartments is damaged to the point that the ship going down. Anyway, a couple of things to keep in mind moving forward. Number one, since this is the first real incident with a shadow fleet vessel, we don’t know how the insurance system is going to work. Normally, if you had a fleet of vessels in this sort of condition and one of them then sunk on its own without getting shot at, you would see an explosion in insurance rates that would probably lead to the decommissioning of every ship of its class. That’s not going to happen this time, because these are ships that should have been decommissioned already. So it’s an open question how Russian insurance is going to pay out because the state created the insurance policy specifically to evade what everybody else normally does on the high seas. And it will be interesting to see if the Russian government actually pays out to cover the environmental solution that will be required for example, for the Omanis. The second thing to watch is the degree to which the Russians do or do not act, will shape what the Ukrainians do and do not do. 

Because if the Russians do not honor their own insurance policy at all, then it’s up to the Ukrainians to probably sink a couple directly. And when that happens, no one’s going to allow these ships anywhere near any of their ports. So we’ve been talking about since the early part of this year how countries are getting more and more aggressive with the shadow fleet. Now we’re seeing the decrepit nature of the vessels probably being their own worst enemy. And as the shadow fleet gets retired, we’re looking at another couple million barrels a day just disappearing. It’s really hard to get a grip on Russian exports right now because the Ukrainians are attacking so much energy infrastructure. But at its peak it was about 5 million barrels a day of raw crude, plus another 2 million barrels a day from Iran. 

We’re looking at losing all of that as this year draws on. So, you know, exciting times. Take care.
Is This the End of U.S. Biofuels?

A green lit gas station with an oil tanker

The U.S. ethanol mandate in the early aughts reshaped American agriculture by tying corn production to fuel production; this saw corn demand double, with roughly half the corn crop now tied to biofuels. So, the case for diverting large amounts of U.S. corn into fuel production is now becoming less clear.

U.S. energy has become independent following the shale revolution. The environmental benefit has been refuted and moving forward, food security will be far more important than biofuels. Allocating large amounts of U.S. corn for fuel production becomes economically and politically difficult when it’s needed (and more profitable) to use for human consumption.

Transcript

Hey all. Peter Zeihan here, coming to you from a snowy Colorado in May. Because that’s what happens in the mountains. Today we’re taking a question from the Patreon crowd, specifically how I see US agriculture evolving over the next several years, specifically in light of the balance among corn and soy and biofuels, with, of course, ethanol being at the top of the list. 

Real quick history lesson for those of you not familiar with the space, the United States has used gasoline and diesel for pretty much everything for transport for the entire industrial age. Until we got to the early 2000, when we got a fuel mandate from the federal government. That said, a certain percentage of most gasoline that you pump has to have a certain percentage of ethanol. 

In most states, it’s in the 10 to 15% range. Now, lots of people have bitched and moan about this for multiple reasons, but basically it took the single largest commodity class that the United States had fuel and cross-referenced it with. The second largest of the United States has, which is row crops, specifically corn. So if you go back to the 80s, a few states in the Midwest, Iowa, of course, did have their own state ethanol mandates. 

But now we had a national one. And from roughly 2004 until today, The total need for corn grown in the United States is roughly doubled, because about half of it is now used for biofuels. Now, that’s not that’s a bit of a blanket statement. The leftover, once you extract the bit that can be turned into ethanol can still be used for animal feed. 

But what it has done is it’s radically changed the agricultural situation of the world’s largest agricultural producer, taking a large chunk of land away from producing stuff for food to instead it being available for fuel that is directly responsible for a lot of the increases around the world. We saw in food prices in the late 2000, because it took ten years for American farmers to produce the volume of crop required, as well as for the United States to build up the infrastructure required. 

Because you don’t take corn to an oil refinery, you have your own ethanol refinery, and then you blend that ethanol in with the fuels at another location. Anyway, in the world that we’re moving into, where agricultural supply chains break down on a global basis, we’re going to be seeing a world that isn’t able to feed itself. And with six or what are we, 7.5 billion people, whatever the number happens to be billions of people. 

And if you have half of the corn crop in the United States going towards fuel instead of human consumption, you can see how this is going to be a problem. It’s just that there aren’t very many countries in the world that have easy access to the inputs, whether it’s the manufactured product, the financial products, or the fertilizer products that are necessary to grow food at scale. 

The United States is by far the largest of them. And if you look at some of the other major producers around the world, most notably China and Brazil, they can’t be agricultural producers without globalization. They import too many of the things that allow agriculture to work. So in a post globalized scenario, if we’re lucky, we’ll only lose a billion people. 

Which brings us back to ethanol. Ethanol is the mandate, because you had a lot of folks in the farm states that were looking for a way to bolster rural incomes in general, and farmers in particular, and the mandate for ethanol and a new one that seems to be being gestating for soy diesel follows similar patterns. But if you remove this, call it conservatively, one third of global food production, then all of a sudden food prices are going to skyrocket. 

And the argument that the United States government should subsidize agriculture to make biofuels kind of falls away. You see, when this all started, the ethanol mandate had a three piece alliance. The farm states obvious environmentalists who thought since it was grown from the ground, it would have a lower carbon footprint. And national security folks who saw this as a way to break our dependance on the Middle East. 

Well, 2026 is not 2000, because now the United States has had the shale revolution. And it’s not just the world’s largest producer of crude oil, and the world’s largest producer of gasoline were the world’s largest exporter of refined product in general. So the national security folks have just kind of faded from this conversation. The environmentalist, who sometimes are a little squeaky with their math, did the math and realize that at best it’s a wash, because the process of growing that amount of corn and moving that amount of corn is actually generating just as much CO2 as what you have to do for gasoline. 

So they went away. So now it’s just the agriculture folks. And if it’s just the agricultural folks, it’s also ultimately going to be about farm income. And if you move into a world where a third of food production falls offline, all of a sudden farmers will be earning less growing food corn for the ethanol mandate than they would growing food for human consumption. 

So regardless of where you are on this equation and what argument you may have had in the past, the macroeconomic situation that led us to doing ethanol at scale is fading pretty quickly. One of the many, many, many outcomes of the Iran wars. We realize just how vulnerable global supply chains were in everything from semiconductors to tractors, because one part of the world produces a lot of the base materials that are used somewhere else. 

That is something that’s going to be reverberating for the rest of the year, and it is something that is really just the tip of the iceberg compared to what is coming. Ethanol was fine in a highly globalized world where there were lots of options. Pretty soon that’s not where we’re going to be.

Global Energy Stressors: Can Anybody Help?

An oil rig on the sunset

Are there any countries that might be able to ease the global energy stress?

Saudi Arabia might be able to ramp up output, but Houthi attacks could take that away in an instant. Producers like Guyana, Brazil, Venezuela, and Canada can only add small, incremental volumes, but most major expansion projects are years away.

So, where does that leave us? The global oil deficit is only going to worsen over the next few months. And with oil market data becoming increasingly unreliable, things are likely already worse than we think…

Transcript

I guess I have a 3.5. This is the backside of that crown. Let’s talk about who might be putting other little volumes in. It’s not a lot. First of all, secondary peak of Bison. Most spare capacity in the world comes from OPEC, specifically from Saudi Arabia or the United Arab Emirates before it left OPEC this year. They’re the only ones who really maintain fields that can turn on off with that in mind. These are all countries that are constrained within, you know, the Saudis would probably be the ones with the best bet. But now that they have to export everything through the Red Sea and the Houthis are regularly attacking ships, most notably tankers, we should actually expect more Saudi crude to go offline rather than come online.

In the Western Hemisphere, we’ve got Guyana, which is a new producer, but their big boost was over the last three years. It’s again only incremental gains, 100,000 here and there, maybe. Venezuela. We, in the best case scenario, now that Maduro has gone might have gotten a fresh million. But now because of the earthquake, if they get half that it’ll be a really good day. Really good year. Brazil no, incremental again. Who am I forgetting? Canada. Canada has audacious plans to massively expand their export capacity, but these plans will not happen this year, next year or the year after. The heavy oil sands of Alberta take years, if not decades, to bring online as well. So the pipeline is only one part of the project.

About the only thing that we might see earlier is that Keystone is being resurrected, and it probably will be built this time, but not this year and probably not next year either. So that’s an issue for 2028, where we might see a half a million to 1 million fresh barrels. That’s not going to help this summer. The only other thing I can think of is Angola.

But Angola is all offshore. It’s all deep and it is failing. So actually the incremental gains that we get out of the Western Hemisphere this year might be enough to compensate for losses out of Angola, but really not much else. It all adds up to a pretty bleak picture for energy markets. I would love to give you pricing advice.

That’s a lie. I’ve no intention of giving you pricing advice, because what’s going on in the markets right now makes very little sense. Keep in mind that oil traders take their price cues from data and the data sucks. Iran doesn’t tell us what they’re producing or what they’re shipping. We’ve got the shadow fleet out of Russia. The Russians aren’t even generating data anymore that you can then look at.

And of course, the Chinese are a bit of a black hole. We know they’ve had a little demand obstruction. We know they’ve had a little fuel switching, but mostly they just don’t publish anything anymore. And it’s unclear if they’re even collecting the data. About the only thing

we can tell is that they have reduced their exports of refined oil product, which has impacted everybody in the Pacific Rim.

And that’s really the end of what we know. Best guess is that the shortage of 10 to 12 million barrels per day is going to go up over the next three months, for the reasons I’ve already talked about. Plus, of course, the Houthis. So the world has significantly less of a buffer now than it did a month ago or three months ago or five months ago.

And at some point that’s going to lead to some sort of market reaction. And when that happens, then we get some of the biggest demand destruction that we’ve seen, at least since the price spikes of 2007 to 2009. So something to look forward to.

Global Energy Stressors: Can Shale Save the World

Close up of shale rock | Licensed by Envato Elements: https://app.envato.com/search/photos/65f10818-30c9-4aa2-8207-5b9626ee65ae?itemType=photos&term=shale

The U.S. shale revolution transformed global energy, but that period of explosive growth is over. Existing pipelines and export infrastructure have reached capacity, meaning future output increases will take a bit of time.

With domestic electricity demand on the rise, U.S. exports will diminish over the coming years. That means America’s ability to offset global energy disruptions is dwindling. Couple that with Asian countries paying premiums for the remaining U.S. LNG, and Europe’s energy picture is only getting worse.

Transcript

Okay. Now. Part three from near the top. Bison peak and all its weird greatness. And then behind me, we’ve got the ten mile range. And the mosquito range. So like quandaries over here and Sherman Sheridan over there. Maybe there…somewhere. Anyway, part three, the United States. Okay. The US shale revolution is different from every other period in energy history, primarily because of the geology.

In a normal Petroleum industry, you’re going to drill through something that’s called a caprock, which is a non-porous rock formation. I got to sit down again so you can see the crown behind me. It’s a non-porous rock formation, ironically. Like these. This is a red granite that oil cannot percolate through, so it builds up pressure behind it. So when you punch through the cap rock, you release that pressure and the well flows, and you maybe get a gusher if you’re lucky.

And even if you’re not, you can always create artificial pressure by pumping water or natural gas or CO2 or something else into the formation to force the oil to the surface. That’s not how a shale revolution well works. In shale, the crude is trapped at the moment of formation into a Petra carbon within the actual rock strata itself. It can’t migrate by definition. So you drill laterally through the formation, have holes in that pipe, and then you pump in pressurized water and sand to crack open the rock. The sand goes into the cracks, and then the little bits of pressure, trillions of little bits of pressure push the water out and back to the surface and it flows by itself.

You can’t do enhanced recovery on a shale. Well, for the most part, there’s some exceptions in there. There’s some gray areas. But anyway, what that means is that instead of the months to years to decades that it takes to bring a conventional well online and then the capital that is required to keep it producing beyond a few years.

Shale is really cheap. It’s up front. All of your costs basically goes into the frack itself, and then you’re done. The downside is that if the shale is in an area where you don’t have existing infrastructure, you have to build a really robust gathering network because you’re going to have a lot more wells traditionally than you will in a traditional field.

You know, there are some of the super fields out there that only have like a dozen wells total. Like that big one offshore in Mexico, which I can’t remember. Cantarell. Cantarell. Ghawar in Saudi Arabia, somewhat similar, whereas you can have dozens, hundreds, thousands of shale wells because they’re only producing a few barrels a day.

That’s gotten better over time, but overall, the logic still holds. Anyway, the United States has been fortunate to this point in that most of the places where we have shale formations, or at least the ones we’ve tapped so far, we also have preexisting infrastructure. So the Permian Basin in West Texas is the best example because it’s been producing crude for

well over a century. But we only started putting shale wells in there in the early 2000. The Bakken in North Dakota. Same general concept. Anyway, what that means is this infrastructure to gather and especially to transport. The crude has been there for decades. And even though those fields by conventional terms have been in decline for decades, as soon as shale came along. There was all this spare capacity and you could just shove whatever you wanted in there. And it wasn’t until about 15, ten years ago that it got so full that we had to actually build new infrastructure. So if you go back and look at the data in some of the early years, we were adding a million barrels per day plus a couple of years I think we even had 2 million barrels per day. That doesn’t happen anymore because now all of the gathering infrastructure, all the transport infrastructure is completely maxed out. And so for the United States to step in and add more oil or natural gas or whatever into the system, we first have to build an entirely new gathering network and then entirely new trunk lines to take it to the ports, and then, in many cases, new ports in order to load it up and send it overseas or refineries or whatever it happens to be.

So the explosive period of U.S. shale oil and natural gas output is now behind us, and we’re now in an incremental phase. And even if that was not the case for specifically for natural gas, we face another problem. Because of the artificial intelligence era, the United States needs massively more electricity. And that’s before you consider preparing for the end of globalization and all the new manufacturing that we’re going to need, and well-being and building things just uses more electricity than digits and numbers.

So whatever spare natural gas production we have right now, we can’t chill down into liquefied form and export because we need to burn it to generate power locally. So what the United States can do to help the world recover or cope with the Iran war and the Ukraine war has already been done, and you’re only going to get incremental increases in US exports from now on, assuming for the moment we even have stuff to export because our power demand is going through the roof.

At the moment, the Asians are bidding up the prices of things like liquefied natural gas. Now, the reason for that is pretty straightforward. Historically speaking, this is a region, especially in Northeast Asia. So China, Japan, Korea, Taiwan that imports 90% of their energy no matter what the form happens to be. And because they import so much, they have to pay more because they just don’t have any good options within 3000 miles.

And so there’s always been this price premium for anyone willing to ship or natural gas to Northeast Asia. The Europeans have always had an easier time of it because they got stuff from Norway and stuff from Libya and stuff from Algeria and stuff from the Russians and stuff from the Middle East. And so their prices have always been at a significant discount to the, the Asians.

And then, of course, the United States has the cheapest energy in the developed world. Well, now that the US stuff is all spoken for, that premium that the Asians have is probably going to spread to Europe, but it just hasn’t yet. So what we’ve seen this year is the Asians paying through the nose. And because they’re paying premiums, all the natural gas and some of the crude that would have normally gone to Europe has made the long trip all the way to Northeast Asia.

But as the Russians vanished from the scene and the Persian Gulf doesn’t recover, we’re looking at that premium spreading to Europe, and we’re looking at prices coming to Europe that they just haven’t seen for the bulk of these past five years, and they’re not ready for it. And it will lead to more deindustrialization impacts and an energy crisis, especially this winter.

And there’s really not a lot that anyone can do about it except for pray that it’s a mild winter, which has happened in the last five years for the Europeans, thank God. But that is a thin reed to base energy security on.

Global Energy Stressors: Europe’s Oil Supply Problem

Oil barrels surrounded by a European flag. Licensed by Envato Elements

As Europe shifts away from Russian natural gas, they have turned to LNG from Qatar to fill the void. Unfortunately, that pivot has brought on its own set of problems.

The Iran War has impacted Qatari exports, leaving the Europeans in a sticky situation. With current storage levels well below average for Europe and Qatar’s force majeure extended to September, the winter months could bring a harsh energy shortage for Europe.

Transcript

Okay, still in bison, peaking on the upper ramparts. That is a McCurdy peak. The double one over there, and I’m now above above Devil’s Playground in just a bunch of really big rocks. Phase two, let’s talk neutral gas, specifically Europe. The Europeans used to get the plurality of their natural gas in piped form from the Russian Federation.

And over the course of the last five years, they’ve been phasing that down to zero. And with a couple of exceptions, they’ve been successful. But that comes at a cost. Not just financial but also security, because things have been so disruptive with the Iran war that the normal path that they had developed to survive in the post Ukraine war environment has been to tap liquefied natural gas from the Persian Gulf, specifically from Qatar.

And Qatar is having some problems. So normally most natural gas in the world, something like 85-90% of it is shipped by pipe. Because it’s a gas, you have to compress it, and it’s difficult to put that into any other form of transport. The one exception, which can get a little ugly from a logistics point of view, by the way, that’s Bison Peak. That’s where we’ll do part three.

A little messy from a logistical point of view is to liquefy it, which basically means you get a metric but ton of electricity, and you operate what is, in essence, a cryogenic freezer and freeze the gas down to something like -270, -300 based on which scale you’re using. And if you do that, it will condense into a liquid.

And then you can put that onto specially designed tankers and send it to any facility that has the technology necessary to regasify it, which isn’t too hard. And then you can treat it like any other normal piped gas within your system. So the Europeans have basically cut Russian pipe gas out and gotten Qatari liquefied natural gas in. One of the reasons this worked is they basically shut down everything in their economy that used natural gas for anything but electricity.

So, for example, the German chemicals industry is basically nosedived, and the combination of switching out supplies and reducing their demand has succeeded. The problem is with Persian Gulf close Qatar’s offline. Qatar got hit very, very hard in the war by Iranian attacks. The specific facility Ras Laffan, that does the natural gas condensation and liquefaction got hit hard. And when the Qataris tried to turn things back on in June, there were several explosions and a lot of people died.

Natural gas is naturally flammable and explosive, and you can imagine what happens with this sort of industrial infrastructure that’s required to turn billions and billions of cubic meters of the stuff into something that you can pour. Since the war began in February, exactly one cargo of Qatari LNG has made it out of the Persian Gulf. That was about three

weeks ago, when we had this nice little moment when traffic in and out of the Gulf reached something like three quarters of what had been pre-war.

We’ve never reached that number again. Most days were less than 10%, with single digits of ships coming or going. There’s no reason to expect that to change anytime soon. It’s going to take a lot more than a cease fire for that to pick back up. And unlike oil, which is relatively easy to produce and store in basically a tank.

Liquefied natural gas, you really can’t do that, especially when there’s a chance that missiles or cruise missiles might hit your storage facility. So Ras Laffan, for all intents and purposes, remains offline. The Qatari this week this, past week declared force majeure extended their force majeure through the end of September. And now we’re talking winter. And right now the winter storage for the Europeans for gas is less than half the normal. It’s the lowest it’s ever been going into a winter. Russian gas is gone, Qatari gas is gone. And as we will talk about in part three, the United States cannot ride to the rescue on this one.

Global Energy Stressors: Kazakh Oil Exports

Flag of Kazakhstan

Global energy markets are all over the place. So, we’re doing a short series on the major energy stressors across the globe and how this all is going to play out. Up first, let’s look at the Ukraine War’s impact on oil exports from Kazakhstan.

Ukraine is ramping up strikes on Russian energy infrastructure, but Kazakhstan depends on those same pipelines, processing facilities, and ports to get its oil out. Exports have already fallen off a cliff, and there’s no reprieve in sight.

Transcript

Hey everybody. Peter Zeihan here, coming to you from the lost wilderness near Denver in Colorado. I am on the lower ramparts of Bison Peak. Bison peaks right over there. That’s my next stop. And today we’re going to stitch together a few things that have come out in this past week that I think are worthy of discussion. First things first. The Kazakhs have published data about how much their exports have been hit by what’s going on with the Ukraine war. Quick recap is that over the course of March through June, the Ukrainians have gotten ever bolder in targeting Russian infrastructure pipes, pumping stations and especially ports. And this really matters for Kazakhstan because it’s landlocked. So it has to use the infrastructure of other people in order to get its stuff to market, by the way. We’re going through the Devil’s Playground area of Bison Peak right now. The key ones are on the Black Sea, specifically Tuapse, and especially Novorossiysk. That is where roughly under normal circumstances, about three quarters of Kazakhstan’s oil exports flow. In addition, the Ukrainians have hit things like processing centers on the Russian side of the Kazakh-Russian border and some of those processing facilities specifically for the Karachaganak field are ones that primarily actually process Kazakh throughput. And without those processing facilities, you can’t pull the sulfur or the natural gas out of the crude stream. And so you can’t put into the normal pipeline network. Anyway, all of these things and more have been hit over and over and over. And according to the Kazakhs, they’ve been looking at a 50 to 70% reduction in output from all of their major fields. So Karachaganak has been hit. The two big ones in the Caspian Sea area are Kashagan, and especially Tengiz and Tengiz actually dates back to the 80s, is the first foreign investment deal ever into the former Soviet Union. The companies that are most affected by this, are Russia’s Lukoil, which is now just an arm of the state, and America’s Chevron and Exxon, the three of those together, the majority of the output here. I’m not counting the Kazakh energy company because it doesn’t do anything it just takes a cut. Anyway, The problem is there are really no good options for the Kazakhs really at all. The in the last month, the Ukrainians have gone from simply attacking physical infrastructure to going after shadow fleet vessels directly both on the Sea of Azov and now in the Black Sea. So I would expect this 50 to 70% drop to be kind of the norm. And this is a country that used to export 2 million barrels a day. And by used to I mean like two months ago. There are really no good alternatives here. Kazakhstan does have a patched together Frankenstein system that exports some crude to China, basically from their eastern and southern regions, but that is typically only a quarter of a million barrels per day. Or on a really, really good day, they might reach a half a million. Everything is really the Black Sea or bust. There is a bypass pipeline in Azerbaijan called the BTC: Baku. Tbilisi Ceyhan starts in Baku. The capital on the Caspian Sea goes through the inner Caucasus zones to Tbilisi, the capital of Georgia, and then on to the Mediterranean port of Ceyhan on the Turkish coast. BTC can handle about a million barrels a day, but it’s primarily an Azerbaijani line and is always at least at half full. So if the Kazakhs were to ship tanker crude across the Caspian Sea, which is its own problem, they could offload at Baku and go to the BTC. But if you take that combined with a Chinese route on a really, really good day, they’re only looking at getting maybe, maybe, maybe, maybe three quarters of a million barrels out. Everything else is going to fall, and it’s highly unlikely that it’s ever going to come back, or at least until such time as the Ukraine war is over. Unlike the Biden administration, that was really hard ass with the Ukrainians about going after Russian infrastructure. The Trump administration really doesn’t care, even though we’re having problems over in the Persian Gulf. And so the Ukrainians are taking out anything they possibly can, and they’ve proven that they can track the tankers that the Russians are using at sea. And now that the ports have been damaged, especially the loading tanks, the tankers can only load up at roughly the pace that the crude is coming in. So it used to be that the tankers would pull up to a dock and you’d have 4 or 5 tanks that were full and they’d all drain down at the same time, and so the tankers could get out of there in just a couple of hours. Now it takes the better part of the day. And with that sort of scenario, the Ukrainians, just using commercial satellite photos know exactly where the tankers are and where to target. So we’re looking at over a million barrels per day going offline, probably permanently. And there’s really nothing we can do about that. That’s piece one.

A Massive Energy Break Coming Soon

An Oil Tanker in the ocean

We’re slipping closer and closer to a major oil supply crunch. With the Persian Gulf still shut in, global inventories almost depleted, and threats to other oil supplies, the world doesn’t have enough oil to keep things running for much longer.

The Chinese have been able to substitute some of their oil demands with coal-based products, but this is just a band-aid. Eventually, oil prices will spike, and certain consumers will no longer be able to afford petroleum products, leading to demand destruction.

Northeast Asia will be hit hardest due to its heavy reliance on imported oil, but even Europe will have issues, despite having alternative supply sources.

Transcript

Hey all, Peter Zeihan here. Coming to you from Colorado. I wanted to give everyone an idea of just when the oil crisis is going to hit, because we’re about their short version is that since the Iran war started, we’ve had somewhere between nine and more, currently about 13 million barrels per day of Persian Gulf crude that isn’t even getting produced, much less exported to the wider world. 

And we are well past the point where the last tankers of exports pre-war have reached their destination. So everyone’s just been burning through stocks and at some point in either June or early July, we’re going to reach basically minimum operating levels for inventories and half the world, if not more. 

We’re looking already about 1.25 billion barrels of crude that haven’t been delivered. With every day goes by. That’s 10 to 13 million barrels of crude that have to be pulled from inventories. And because prices haven’t dropped, which is kind of weird. Demand really hasn’t dropped all that much. We’ve seen a little bit movement in some subsectors, like say, jet fuel and diesel, but for the most part, people are continuing to consume crude like this isn’t a long term problem. 

Oh my god. Anyway, at some point in June or early July, we’re going to hit the wall. The primary reasons why it hasn’t happened already is we’ve got two little factors in play. The first are the strategic reserve releases that the IEA approved two months ago. Now, in the case of the United States, this has really helped out Europe because the United States is a net exporter of crude and refined product by a large margin. 

So we don’t need the crude that is being released. So roughly 2 to 2.5 barrels a day of crude from our strategic petroleum reserve are just crossing the Atlantic and helping out the Europeans. And since the Europeans are so much more efficient at energy use than we are, that has really helped them kind of square the circle in the mid-term. 

It won’t last much longer, but for now it’s holding on the Asian side. Something else has helped out. That’s a little odd. 

When you make petrochemicals, you usually use a mix of feedstocks. You turn oil into something called naphtha. That’s your primary feedstock, but you also use liquefied petroleum gas like ethane and propane and butane. Some of these have partial substitutes, specifically the naphtha. 

And what the Chinese are doing is trying to cut out as much naphtha from their system as they can, and instead substitute it with a kind of processed liquefied coal. Now, this is wildly inefficient and expensive and especially polluting. But when you’re in a throughput driven system like the Chinese, it’s not so big of a deal. So headline. 

The Chinese petrochemical sector uses about 4 million barrels a day of product, of which about half, maybe a little less, is naphtha. And they’ve been able to substitute coal for maybe a third to half of that which is bought Asia. A little bit of wiggle room and has prevented the Chinese from having runaway price increases. You combine that with their large scale application of very, very, very small electric vehicles and a grid that primarily runs on coal anyway, and they’ve bought some more buffer that way too. 

But all of this is going to evaporate over the course of the next 3 to 6 weeks. So we’re very close to the break assuming nothing else goes wrong. And as we have seen in the past, that if we do get into a hot war situation again, the Iranians have easily demonstrated that they can hit any part of the export infrastructure from the Persian Gulf that bypasses the Strait of Hormuz, specifically the bypass pipelines of the United Arab Emirates and the Saudis have so were, ironically, in probably the best that can be hoped for right now. 

No hostilities, but the Persian Gulf still closed. If the Persian Gulf were to reopen tomorrow, it would be months before any new crude would flow, because it just takes that long to turn these fields back on and in some cases, years. So the late June and into July deadline is probably going to happen regardless of what happens with the negotiations that are ebbing and flowing back and forth. So get ready for a fun summer. 

How this usually happens is when you’ve got this sort of disruption. Prices go through the roof because there just isn’t any throughput. It’s not that people have cut refinery runs for the most part. It’s just that we’re not going to have feedstock. And when that happens, you get this lovely thing called demand destruction, where prices rise to a point that some parts of the economy, some people in some parts of the world simply can’t afford the crude derived products at all. 

And when that happens, their demand is destroyed. Till such time as prices fall back into line. The last time the world experienced this scale of disruption, it wasn’t the oil crises in the 70s or the 80s. It was World War two when everything got sunk. So historically unprecedented is the term. And keep in mind that with the global happened, some version of this was going to happen in a large scale. 

Regardless, the parts of the world are going to be most affected. At the top of the list is Northeast Asia, because this is an area that imports well over 90% of their crude. And until recently, all of that crude has really come from the Persian Gulf. They do get a little bit of a kicker from the former Soviet Union now, a little bit from the Western Hemisphere, but not enough to make a material difference. 

And the second worst will be Europe, where they also import 90% of their crude. But they have the potential of tapping more regions, most notably North America and North Africa and West Africa. So here we go.

Using U.S. Energy as Leverage

Two LNG tankers at port

Trade relations between the U.S. and Europe are on the fritz. The latest in all the noise is the suggestion that the U.S. could restrict LNG exports to the EU if trade negotiations break down.

This is a low blow, as Europe imports most of its gas. And if you haven’t noticed…the world is in a bit of a shortage at the moment. Cutting off exports would be legally and practically difficult, but a distressing notion nonetheless.

While the idea of using U.S. energy dominance as a negotiating tool isn’t surprising, I had originally pictured this strategy as being reserved for rivals, not allies. But there’s the Trump administration for you.

Transcript

Hey, all. Peter Zeihan here. Coming to you from Pozza Della Cava caves in Ovierto, Italy. Today we’re looking at some of the strange things that are happening in US European relations. As you may or may not remember, the Trump administration is carrying out 200 simultaneous trade talks and none of them are really going anywhere, which means it’s really up to secondary officials that normally wouldn’t have much power in negotiations to kind of set terms. 

And one of them, Andrew Pozner, the US ambassador to Europe, has said that if talks between the Trump administration in Europe don’t go well on things like, well, this is neat on things like auto tariff levels that the United States is going to stop sending liquefied natural gas to the continent. Now, that’s it’s a total dick move, but that doesn’t mean it won’t work. 

Two things. Number one, Europe imports nearly 90% of their natural gas. And before the Ukraine war, it was more or less an even split between stuff from North Africa liquefied natural gas. It was imported from multiple countries, stuff from the former Soviet Union and then Norway. What’s happened now is that two of those got away because of the Ukraine war. The flows from Russia have stopped and because of the Iran worshiping strait, a former flows from Qatar, which is the largest LNG supplier to Europe pre-war, have also stopped. That means US natural gas is one of the few sources of energy that the Europeans can still access, and if that is to go away for any reason, then the Europeans are kind of screwed. 

So that’s kind of piece one. Piece two is how this would happen. It’s kind of difficult to imagine. That doesn’t mean it can’t happen, though. The issue is private enterprise. The United States doesn’t have a state or company. It just has private companies that are buying natural gas on the American market, cooling other facilities, typically on the Texas or Louisiana coast, and then shipping it out. So if the United States was going to bar those companies from selling to Europe as part of negotiations, there were definitely a bevy of lawsuits. But if there’s one thing about this administration that we really do understand is it’s deeply disinterested in general business conditions or the role the government plays in business, and it’s really not constrained by legal norms at all. 

So while from a clear, clean legal point of view, I don’t see how this would happen, I don’t think that would really dissuade the federal government under this administration at all. So will this work? This is one of the things that in my projects, in my books in the past, pre Trump, I said we should probably expect that the United States will try to leverage its energy, security and economic strength in order to get whatever it wants out of anyone. It’s just a little frustrating from my point of view, to see this used against allies as opposed to potential foes, but, you know, bygones.

Impacts on the U.S. Power Grid from the Iran War

Satellite view of north american lights and energy

The U.S. is relatively insulated from the conflict in Iran and the closure of the Strait of Hormuz, since it’s a net exporter of nearly every major energy source. Most other countries aren’t so lucky…

However, there are plenty of indirect risks for the U.S. Global energy shortages could spike commodity prices (like coal) and disrupt supply chains; this would affect key U.S. imports like aluminum, copper, and transformers.

So, the U.S. power grid is likely safe in the near-term, but secondary effects on infrastructure and manufacturing could complicate things down the line.

Transcript

Hey everybody. Peter Zeihan here, coming to you from Colorado. Today, we’re taking a question from the Patreon page. Specifically, it’s whether or not I think that there are any parts of the US power grid that are particularly vulnerable to what’s going on in Iran right now, because of the closure of the Strait of Hormuz, for example, 20% of global liquefied natural gas is locked in. 

And if you happen to be an importer of that, that’s a bit of a problem in any number of ways, because you can’t keep the lights on. Nothing else really matters. This is something where I’ve got some good Not only is the United States insulated because it’s in a different hemisphere, but the United States is a net exporter of every type of energy, whether that is raw electricity that’s already been generated, natural gas or jet fuel, naphtha, coal, all of it. 

Which means that unless there is a direct price link back to the United States through something that is used to make electricity, you’re kind of in the clear. The only fuel out there that really has that sort of link is liquefied natural gas. And the United States is the world’s largest exporter of that now. So there’s at the moment, no direct link. 

Now there’s plenty of indirect links. So for example, if you use coal in the United States and the United States is a coal exporter and the price of coal goes up on a global basis because of energy shortages related to other countries having power problems, and you might feel indirectly, or if you want to take a longer step in something, we’re all going to feel probably by the end of the year, the sort of rolling energy crisis that we’re starting to see in East Asia and to a lesser degree in is absolutely going to hit manufacturers markets. 

And the United States imports. A lot of the things that we use to stabilize our own power grid, whether that’s aluminum cabling for things like power lines, copper for anything that goes into electronics, and more advanced pieces of equipment like transformers, which take over a year to build. Because of the complexity, we will be feeling that in our power grid, but that is very indirect. 

That is not this month. That is a problem for probably the fourth quarter of this year. So for what it’s worth. I do have a little bit of good news from time to time.